 By
Secret Reporters
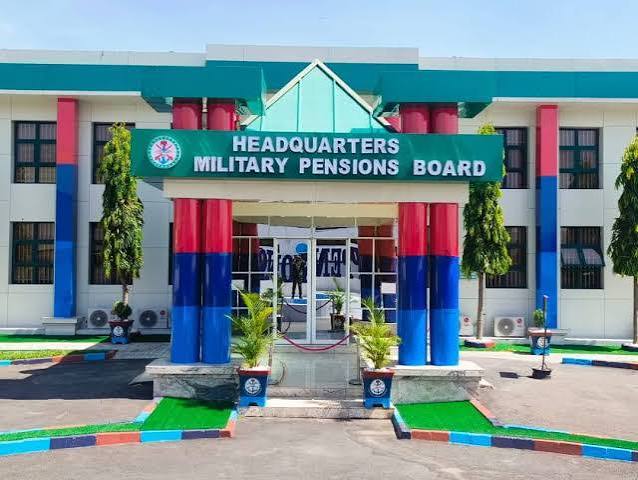
The Military Pension Board, Abuja, failed to deduct ₦419,238.42 in stamp duties from four contracts awarded in 2020, leaving the statutory charges uncollected and unremitted to the relevant tax authorities, according to findings on the Board’s financial transactions.
Similarly, the amount also represents the one per cent stamp duty that was expected to be deducted from the four contracts. However, the deductions were not made, and no explanation was provided for the failure to collect the money. The issue was identified under Treasury Circular TRY A1&B1/2017 and Financial Regulations 2009, paragraph 620, which were cited in relation to the required handling of stamp duties. The provisions formed the basis for questioning why the statutory charge was not deducted from the contracts.
More so, the ₦419,238.42 outstanding amount may appear relatively small compared with larger public-sector financial cases, but the issue goes beyond the amount involved. Stamp duties and other statutory charges are expected to be handled in line with applicable financial requirements. When such deductions are omitted, the government may lose revenue that should have been collected from transactions.
In this case, the findings identified four contracts from the 2020 financial year on which the one per cent stamp duty was neither deducted nor remitted. The document did not provide the names of the contractors, the individual contract values or the specific reasons the deductions were omitted. It also did not establish what happened to the money beyond noting that the required stamp duty was not collected.
Furthermore, this failure was identified as a potential loss of government revenue. The possibility of diversion of public funds was also listed among the risks associated with the matter. However, the findings did not establish that the money had been deliberately diverted or identify any individual responsible for the omission. The Board’s management did not provide a response to explain why the stamp duty was not deducted on the four contracts. Consequently, the circumstances surrounding the failure remained unexplained in the information provided.
The recommendation was for the Military Pension Board to recover the full ₦419,238.42 and remit the amount to the appropriate tax authorities. The document further stated that sanctions under Financial Regulations 2009, paragraphs 3112 and 3129, could apply if the matter was not satisfactorily addressed.